How Much Does It Actually Cost to Move Up in Kelowna?
If you already own a home, the price of your next home does not tell you what moving will actually cost. Your current equity, mortgage balance, selling and buying costs, and the difference between what you sell and buy for matter more.
A $1.1 million home might sound completely out of reach.
But if you already own a home in Kelowna or the Okanagan, that is probably the wrong number to start with.
The better question is:
What would I actually need to borrow to make the move?
That can be a very different number.
A conversation that got me thinking about this
Maddie’s old university soccer coach was visiting from Saskatchewan recently, and we got talking about Kelowna home prices.
They were surprised by what homes cost here.
Coming from Saskatchewan myself, I understand the reaction. Looking at a $1 million or $1.2 million home can create some serious sticker shock.
But there is an important difference between someone trying to buy that home from scratch and someone who has owned in the Okanagan for years.
The existing homeowner may have something working in their favour: equity.
They have been paying down their mortgage, and depending on when and where they bought, their property may also be worth considerably more than they paid for it.
That equity can change the next purchase.
A $1.1 million home doesn't necessarily mean a $1.1 million mortgage
Here is a simplified example.
Take a West Kelowna home that sold for $475,000 in 2015 and again for $905,000 in 2026.
For illustration, assume the current owner still owes $289,000. That is not the actual mortgage on that property.
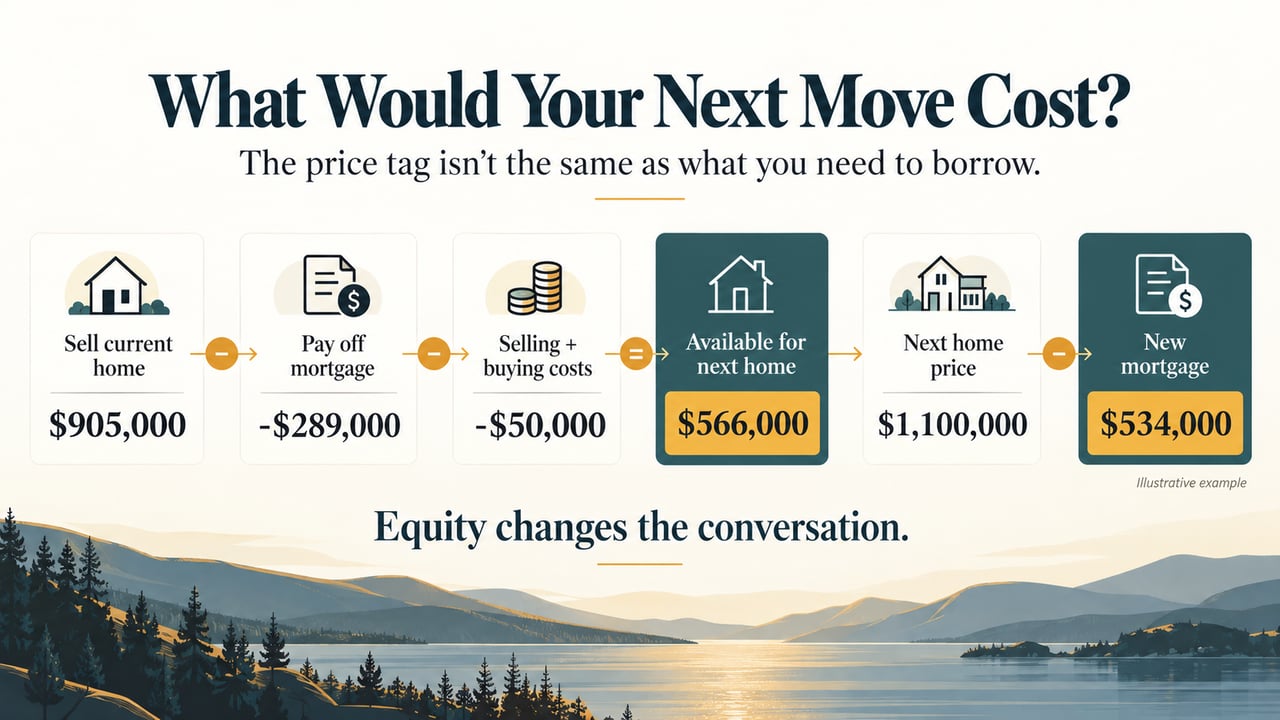
If they sold for $905,000:
Step | Amount |
|---|---|
Sale price | $905,000 |
Mortgage payout | -$289,000 |
Allowance for selling and buying costs | -$50,000 |
Available toward next home | $566,000 |
Now suppose the next home costs $1.1 million.
After applying $566,000 toward the purchase, the new mortgage would be approximately: $534,000.
That is still a significant mortgage.
But it is a very different conversation than saying:
“I can't afford a $1.1 million house.”
The real question is whether you can comfortably handle roughly $534,000 of mortgage debt and whether what you gain from the move is worth the additional cost.
What does the extra mortgage cost each month?
The existing mortgage in this example is $289,000.
The new mortgage would be $534,000.
That means the move adds approximately $245,000 of mortgage debt, after accounting for our simplified $50,000 cost allowance.
Using an illustrative mortgage rate of 4.7% and a 25-year amortization:
- $289,000 mortgage = approximately $1,639/month
- $534,000 mortgage = approximately $3,029/month
- Difference = approximately $1,390/month
These figures are illustrations only. Your actual payment will depend on your mortgage terms, rate, amortization and financing.
Now we have a much better question:
Would what you gain from moving be worth roughly another $1,390 per month?
Maybe it gets you another bedroom.
A better layout.
A bigger garage.
A suite.
A yard.
A different location.
Or maybe you look at the numbers and decide your current home works pretty well after all.
Both can be good decisions.
The price gap matters when you're selling and buying
There is another part of move-up math that homeowners sometimes miss.
Your selling price should not be looked at by itself.
Suppose you expected to sell your current home for $900,000 and buy the next one for $1.2 million.
That is a $300,000 gap.
Now imagine the market softens.
You sell for $880,000, which is $20,000 less than expected.
That doesn't sound great.
But if you can now buy the next home for $1.16 million instead of $1.2 million, you saved $40,000 on the purchase.
Your new gap is $280,000.
You sold for $20,000 less, but the move itself became $20,000 cheaper before transaction costs.
This doesn't happen evenly across every neighbourhood or property type. A condo, townhouse, entry-level detached home and $1.5 million home can all move differently.
That is why I would look at both sides of the transaction before deciding whether a market is good or bad for your move.
Equity doesn't automatically mean you should move
There is a danger in looking at a big equity number and treating it like free money.
It isn't.
You still need to consider:
- the new mortgage payment
- property taxes
- insurance
- utilities
- maintenance
- strata fees, if applicable
- transaction costs
- emergency savings
- whether you can comfortably qualify for the financing
And there is an opportunity cost.
Putting another $200,000 or $300,000 into a home means that money cannot be used somewhere else.
The move has to make sense beyond simply being possible.
The same calculation works in reverse for downsizers
For someone downsizing, the goal may be completely different.
Imagine selling for $1 million.
There is $150,000 left on the mortgage.
Allow $50,000 for selling and buying costs.
That leaves approximately $800,000.
If the next home costs $650,000, the owner could buy it without a mortgage and have approximately $150,000 remaining in cash.
That could be used for retirement, travel, investing or simply creating more breathing room.
Of course, other debts or expenses could reduce that amount, and the ongoing costs of the next home still matter.
But again, the important number isn't simply:
“I sold for $1 million.”
It is:
What did the move actually change financially?
What about first-time buyers?
First-time buyers don't have years of home equity to bring to the next purchase.
That makes the first step harder.
But it also helps explain why your first home doesn't necessarily need to be your forever home.
The goal shouldn't be to assume prices will keep climbing and bail you out later.
Instead, a first purchase can potentially give you time to:
- pay down mortgage principal
- build savings
- increase income
- improve your financial position
- eventually create more choices
You have to start somewhere.
The important part is buying something you can reasonably afford and hold, rather than stretching for the home you hope to own ten years from now.
The four numbers I'd look at before moving
If you're thinking about moving up or downsizing, I would start with four numbers:
1. What could your current home realistically sell for?
Not the highest comparable. Not your assessment. What would today's buyers likely pay?
2. What do you still owe?
Include the mortgage and any other debt that would need to be dealt with through the move.
3. What will the move cost?
Selling costs, legal costs, applicable taxes, moving expenses and other purchase costs need to be considered.
4. What does the next home actually cost you?
Calculate the new mortgage and monthly carrying costs after applying your available equity.
That gives you something much more useful than comparing two asking prices.
Sometimes the answer is to stay
Running these numbers isn't about convincing yourself to move.
Sometimes the calculation tells you the opposite.
Maybe another $1,400 per month isn't worth getting another bedroom.
Maybe the better move is renovating.
Maybe you want to pay down more debt first.
Maybe the right property isn't available yet.
Or maybe you discover that a move you assumed was impossible is actually manageable.
That is the point of doing the math.
Don't decide whether the next home is out of reach based on its price tag. Work out what the move actually changes for you.
I built a Move-Up Equity Calculator for exactly this reason. You can enter your current home value, mortgage balance, estimated costs and next purchase price to see what the move could look like.
Try the Move-Up Equity Calculator: [ CALCULATOR LINK]
The calculator is a planning tool, not mortgage or financial advice. For actual financing and qualification, confirm the numbers with your lender or mortgage professional.
About Mark
Mark Coons Personal Real Estate Corporation
Mark Coons, BBA, CE
REALTOR® | eXp Realty Kelowna
Team Lead, Selling Okanagan Group
Relocated to Kelowna in 2018
778-946-6454
[email protected]